On October 14, 2026, Blockworks Advisory published an in-depth analytical report on artificial intelligence inference service providers in the cryptocurrency sector. The report offers a candid and realistic perspective: despite the promises of decentralized compute networks, the crypto-AI sector currently commands only a tiny fraction of the global market and remains operational largely thanks to substantial token emissions.
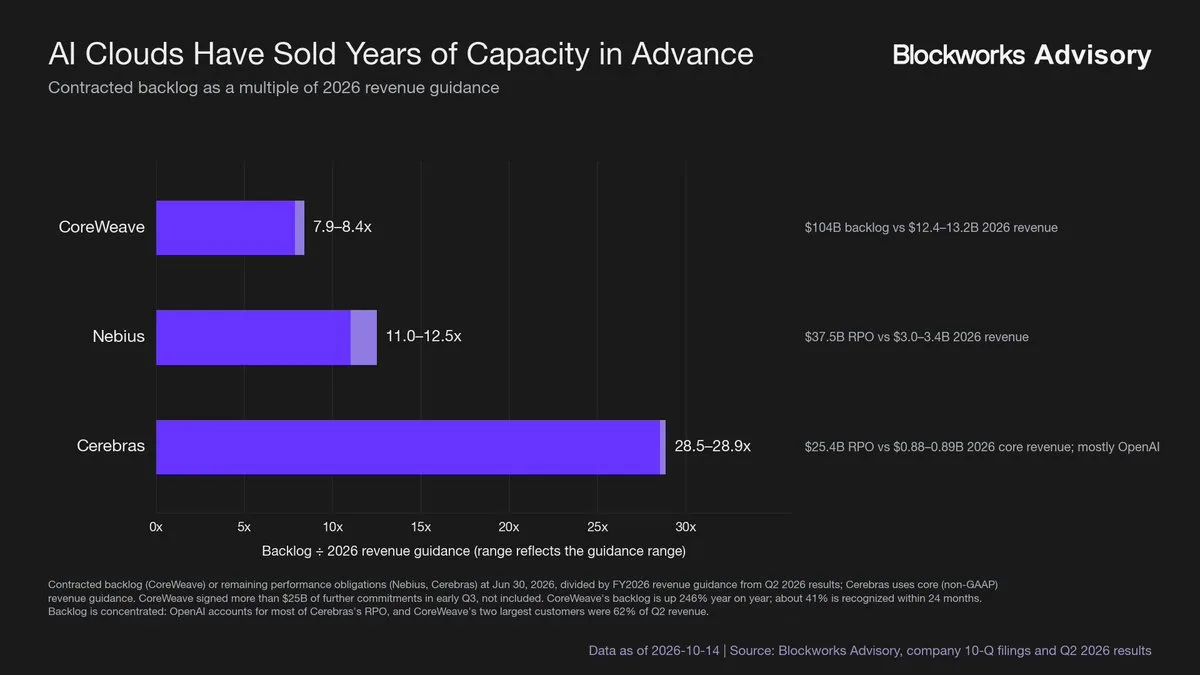
The report focuses on 7 crypto-native providers offering services through the OpenRouter intermediary platform: Venice, Phala, Darkbloom, io.net, AkashML, NEAR AI, and Chutes. This is the only neutral venue that publishes transparent, daily provider- and model-level data.
Modest scale amid the traditional infrastructure investment boom
The worldwide push to build AI data center infrastructure is underway on a multi-trillion-dollar scale, yet computing demand continues to outstrip supply. Set against this vast backdrop, the total liquid asset value across crypto AI stands at approximately $24.9 billion. That figure is smaller even than the valuation of a single traditional AI infrastructure company like Crusoe at $30.9 billion. Notably, no decentralized compute network has reported verified revenue exceeding a few tens of millions of dollars.
On the OpenRouter model exchange, the 7 crypto providers collectively served about 211 billion tokens per day over the past month. This accounted for a mere roughly 1% of the platform’s total daily processing volume of 21.9 trillion tokens.
OpenRouter itself represents only a small slice of global demand. By comparison, Google alone reported processing around 1.3 quadrillion tokens per month in October 2025, double OpenRouter’s volume, while total global token consumption is estimated at around 400 trillion tokens per day.
Divergent strategies, but fragile competitive moats
Crypto-native projects are seeking differentiation in various ways: pooling distributed GPUs, leveraging consumer Apple Silicon chips, accepting stablecoin payments, guaranteeing privacy, or hosting uncensored models. However, operational data reveals marked divergences among their business models:
Venice leads commercially through its proprietary consumer app
Venice posted the strongest commercial results in the cohort, with self-reported annualized revenue reaching $100 million in July 2026. However, this revenue is derived primarily from its proprietary consumer-facing front-end app at higher prices per token. The OpenRouter channel contributed less than 10% of revenue, serving roughly 87 billion tokens daily. Notably, to provide hardware-secured compute, Venice effectively resells capacity procured from NEAR AI at list price plus 7% and from Phala at a 25% premium.
Phala serves as a confidential router
Phala reached a daily throughput of 54.6 billion tokens on OpenRouter, logging a 150% increase over the past 30 days and commanding the highest average price in the group at $0.36 per million tokens thanks to its confidential computing (TEE) label. However, Phala’s routing gateway shows that the majority of traffic runs on partner hardware: about one-third executes on Chutes, 15% on NEAR AI, and 40% passes through RedPill routes without hardware security.
Chutes operates on massive token emissions
Chutes, the SN64 subnet on Bittensor, runs around 4,350 GPUs with pricing consistently ranked among the top 3 cheapest on OpenRouter. These low prices are subsidized directly by the network: capturing 6% to 9% of Bittensor’s emissions with the TAO token trading around $276, the subnet receives token allocations worth $21 million to $33 million per year. Meanwhile, on-chain revenue recorded by DefiLlama stands at only around $4.5 million annually. Token emissions outpace actual revenue by a factor of 5 to 7.
AkashML scales back hardware subsidies
As the longest-standing GPU marketplace, Akash currently operates 283 active GPUs and generates approximately $3.7 million in annual rental fees. The network no longer runs token subsidy programs for hardware providers in 2026, transitioning instead to a mechanism that uses customer payments to buy back and burn AKT tokens.
Darkbloom taps Mac hardware
Part of the EigenCloud ecosystem, Darkbloom charted a distinct path by paying cash to enlist 1,143 Macs powered by Apple Silicon to serve smaller models. Darkbloom’s pricing is highly competitive, but its latency is 3 to 17 times higher than rivals using dedicated GPUs, prompting OpenRouter’s routing algorithms to rank it with lower priority. The project relies on the Yukon open research platform for community-driven decoder software optimizations to offset this limitation.
Subsidy burdens and questions over long-term defensibility
The Blockworks Advisory report categorizes subsidy reliance into three groups: hardware supply subsidies, demand-stimulating user price subsidies, and pay-as-you-go models driven by actual demand. Projects like Chutes and Phala rely heavily on token emissions to retain machine operators or sell compute below cost.
Using token emissions to absorb losses can help a network bootstrap supply quickly during early phases. But as token inflation tapers off or the market enters a downturn, providers lacking organic cash flow from paying customers will face intense pressure to sustain their infrastructure.
The Blockworks Advisory report includes a disclosure that it was commissioned by Eigen Labs.
The decentralized inference race continues to showcase novel experiments in hardware aggregation and routing. Nonetheless, as technical barriers gradually diminish and traditional providers also adopt stablecoin payments and open-source models, the question remains: how will crypto networks defend their market share once token subsidies run dry?